

PayPal Business
by PayPal Mobile
3.8
- Safety
- 100% Safe
- Category
- Business
- Ratings
- 3.8
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
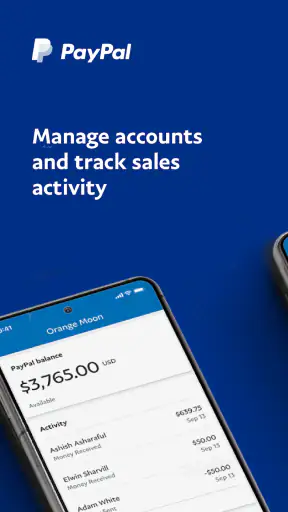
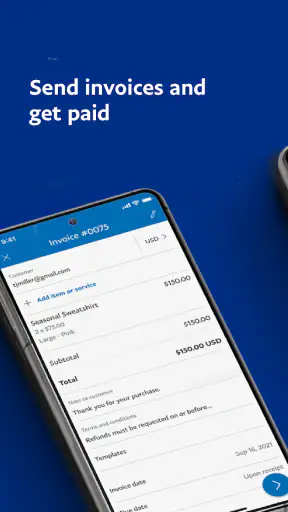
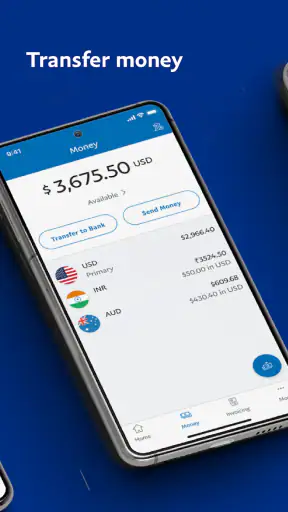
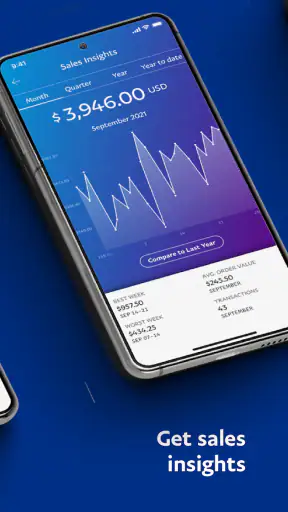
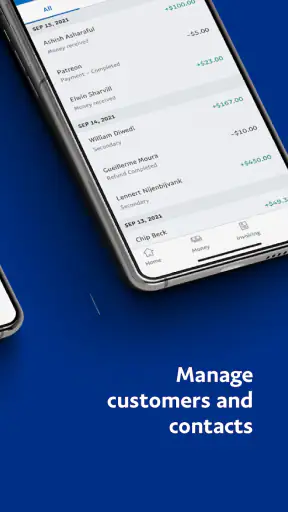
 Analysis by Getfullapps
Running a small business often means switching between customer messages, payment records, invoices, and everyday banking tasks. PayPal Business is designed to bring much of that work into one mobile app, and I found its main appeal in that practical focus rather than in a long list of extras. It is a free business app from PayPal Mobile, available to everyone, and it has become a familiar option for sellers who already use PayPal to receive money.
My experience with it is best summed up this way: it can make routine payment administration easier, but it is not a complete replacement for accounting software, a dedicated invoicing platform, or a full business bank account. The app is strongest when you need to create and manage invoices while keeping an eye on PayPal activity from your phone. It is less convincing if your business needs deep reporting, complex stock control, detailed expense management, or complete control over every financial workflow.
What the app feels like in everyday business use
The first thing I noticed is that PayPal Business is built around quick decisions. A customer asks for an invoice, a payment arrives, or I need to check whether something has been paid, and the app is intended to let me handle that without sitting at a computer. That makes it particularly suitable for freelancers, independent sellers, consultants, tradespeople, and small teams that do not have a separate finance department.
The app belongs to the business category, but its practical role is narrower than that label might suggest. I would think of it as a mobile control point for PayPal-based transactions, not as an all-purpose business management suite. That distinction matters because a person looking for payroll, inventory, tax preparation, or full bookkeeping may expect more than this app is designed to provide.
PayPal Business has been available since November 28, 2016, and the current version is 2025.04.24. It supports Android 6.0 and later, which makes it accessible on many older Android devices. The broad device support is useful for people who keep an older phone for work, although performance can naturally depend on the handset, operating system condition, and connection quality.
The app is free to install, which lowers the barrier to trying it. That does not mean every business transaction is cost-free; payment services can involve their own charges and conditions, so I would always check the applicable terms for the type of payment I plan to accept. The important point is that the app itself does not require an upfront purchase, making it easy to test alongside an existing PayPal business account.
Its audience is already substantial. The app has more than ten million installs, a 3.8 average rating, about 109 thousand ratings, and around 9.8 thousand written reviews. I do not read those figures as proof that it will suit everyone, but they do show that this is an established tool rather than an experimental business app with an untested audience.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Trust starts with the account, not the interface
When money is involved, I pay more attention to account boundaries than to visual polish. The useful question is not simply whether an app looks professional, but whether I can tell which account I am using, what action I am about to take, and whether a payment or invoice is being handled in the right business context.
That is where the PayPal identity helps. If I already use PayPal for business payments, staying within the same ecosystem can reduce the confusion that comes from moving between unrelated payment apps. At the same time, this concentration means the PayPal account becomes especially important. A user should treat login protection, recovery details, and device access as part of the business workflow rather than as minor setup tasks.
I would not install the app casually on a shared phone and leave the account open. A business payment account can expose sensitive transaction details, customer information, and money movement activity. Using a device lock, keeping the operating system current, and signing out or protecting the phone when other people can access it are sensible habits. These are not glamorous features, but they matter more than a decorative dashboard.
The developer shown for the app is PayPal Mobile, which gives the product a clear connection to the PayPal service. That connection is reassuring for an existing PayPal merchant, but it also means I would avoid treating the app as an isolated tool. Changes to the account, payment status, or available business functions may affect how the mobile experience works, so I would review the account screens carefully instead of assuming that every option has the same meaning as it would in another finance app.
Invoices are where the app earns its place
The most obvious reason to use PayPal Business is invoice handling. For a small service business, the workflow can be straightforward: create an invoice after completing a job, check the details before sending it, and return to the app later to monitor its status. Being able to do that from a phone is valuable when work happens away from a desk.
I find the mobile approach especially useful for short, clearly defined jobs. Imagine a freelance photographer finishing a small event, confirming the agreed amount, and preparing an invoice before leaving the venue. Or picture a repair professional who wants to send a payment request from the customer’s driveway rather than writing down details and remembering them later. In those moments, speed reduces the chance of forgetting an invoice or mixing it up with another customer.
My practical tip is to prepare the information before opening the invoice screen. Have the customer’s details, service description, amount, and any relevant terms ready. Mobile entry is convenient, but it is also easier to make a small typing mistake on a phone. A quick review before sending is worth the extra moment, particularly when several invoices look similar.
Another useful habit is to treat invoice status as a follow-up tool, not as a substitute for bookkeeping. I would use the app to see what needs attention, then record the transaction in whatever accounting process the business already uses. This prevents a common mistake: assuming that a payment app’s activity view automatically provides a complete financial record for taxes, expenses, refunds, and reconciliation.
For very simple invoicing, this can be enough. If I only send occasional invoices and want the customer to pay through PayPal, the mobile workflow feels more direct than maintaining a separate invoicing service. However, a business with recurring billing, detailed line-item structures, multiple tax rules, or extensive client records may eventually need a specialist platform with more control.
Where the mobile workflow saves time—and where it does not
The app makes sense when the phone is already part of the job. A market seller, independent tutor, home-based maker, or consultant can check payment activity between appointments instead of waiting until the end of the day. That immediacy can be useful for customer conversations, especially when someone asks whether a payment has arrived.
Still, I would be careful about using a payment status as the only basis for handing over valuable goods or starting expensive work. A quick screen glance is helpful, but business decisions should be based on the actual status shown in the account and on the business’s own payment and delivery rules. If something looks delayed, reversed, unfamiliar, or inconsistent with the customer’s message, I would pause and investigate rather than relying on a screenshot or verbal assurance.
This is one of the app’s less obvious trade-offs. Mobile access encourages speed, but financial work benefits from deliberate checking. The best workflow is not “open the app and approve everything quickly.” It is “use the app to see the current situation, then verify the details before acting.” That distinction is particularly important on a small screen, where long names, descriptions, or transaction details may require extra attention.
I also would not expect the app to replace a desktop view for every task. A phone is excellent for checking a recent item, sending a simple invoice, or responding to a customer while away from the office. It is less comfortable for reviewing a large set of transactions, comparing periods, or doing detailed administrative work. A business that processes many payments may prefer to use the mobile app for urgent checks and a broader tool for regular reconciliation.
Data-sensitive moments deserve extra care
Business payment activity naturally involves information that should be handled carefully. Customer names, invoice descriptions, amounts, and account activity can all reveal details about a business and its clients. I would avoid entering unnecessary personal information into an invoice description. A clear description is useful; an overly detailed note containing private information is not.
Before sending an invoice, I would check the recipient, amount, currency if applicable, service wording, and any customer-facing message. This is more than proofreading. An invoice can become part of a customer’s records, so an incorrect description or wrong recipient can create confusion that is harder to repair later. The app’s convenience is most valuable when it is paired with a repeatable checking routine.
I would also separate business and personal activity as much as possible. Mixing the two may be tempting when a business is very small, but it makes later review harder and can blur the purpose of transactions. Using the appropriate PayPal business account and keeping descriptions consistent gives me a clearer trail when I need to understand what happened.
Notifications deserve the same attention. A notification can be convenient when I am waiting for a payment, but I would not treat a message preview as the full transaction record. On a shared or visible phone, previews may also expose customer or business information. Adjusting notification visibility through the phone’s controls is a sensible privacy choice for anyone who handles payments in public or around colleagues.
I also recommend being cautious with unexpected messages that appear to refer to an invoice or payment. Instead of opening a suspicious message and following its instructions, I would open the app directly and inspect the account there. This keeps the decision inside the familiar account environment and reduces the chance of confusing a message with a confirmed transaction.
Controls and user choice matter more than convenience
A business app should make it clear when I am viewing information, sending an invoice, or taking an action that affects money. My preferred approach is to slow down at every point where the action becomes irreversible or customer-facing. I check the account identity, review the recipient, and confirm the amount before sending.
The app is most comfortable for a sole trader who personally manages the account. In a larger business, the question becomes who should be allowed to view activity or perform actions. I would not share a single login casually among staff. If several people need access, the business should use the account’s available management and security arrangements rather than passing passwords around. The exact options can depend on the account setup, so I would inspect the controls available to that business before assigning responsibilities.
This is also where the app may not be the right central system. A growing company may need approval steps, role-based access, audit procedures, and formal separation between preparing an invoice and releasing a payment. A mobile PayPal workflow can support such a business, but it should not automatically become the only control layer.
For personal agency, I like that the phone makes the account accessible without forcing me to wait for office hours or a desktop session. But access is not the same as understanding. I would take time to inspect account activity, review unfamiliar entries, and keep contact details current so that account notices and recovery steps reach the right person.
Another practical tip is to create a simple internal routine around the app. For example, I might prepare invoices during the day, review outstanding items at a fixed time, and reconcile completed payments separately. That prevents constant checking from becoming a distraction and gives the business a clearer record of what has been handled.
How it compares with common alternatives
Compared with a traditional bank app, PayPal Business is more focused on payment requests and PayPal-based business activity. A bank app may be better for broader cash management, transfers, and account balances, while this app is more useful when the customer-facing payment process already runs through PayPal.
Compared with a dedicated invoicing service, PayPal Business can feel simpler for occasional invoices because the payment destination and business account are closely connected. A specialist invoicing product is usually the better direction when I need extensive templates, recurring billing, detailed client histories, tax workflows, time tracking, or structured reporting. The trade-off is that adding another service can create another account, another interface, and another place to reconcile payments.
Compared with a card terminal or point-of-sale system, the app is not the same kind of tool. A physical retail operation may need product catalogs, stock counts, receipts, staff permissions, and checkout hardware. PayPal Business is more appealing for service work, remote selling, online requests, and businesses where an invoice or payment request is the natural starting point.
Compared with a spreadsheet, the app offers a more direct connection to payment activity, but a spreadsheet can still be useful for planning, categorizing, and reconciling. I would not choose between them as if one must eliminate the other. For a small business, the sensible arrangement may be to use PayPal Business for customer-facing payment tasks and a separate record for the wider financial picture.
Who should use it and who should look elsewhere
I would recommend trying PayPal Business if I were advising a freelancer, independent consultant, occasional seller, or small service provider who already wants to work through PayPal. It is particularly convenient for someone who sends a manageable number of invoices and needs to check activity while moving between jobs.
I would be more cautious for a company with several employees, complicated billing rules, high transaction volume, or a requirement for formal financial controls. The app may still be useful as a mobile companion, but I would not make it the sole system without checking how well it fits the company’s approval, reporting, and record-keeping needs.
I would also skip it if the business does not use PayPal and has no reason to add another payment ecosystem. Installing a business app simply because it is free can create extra administrative work. The value comes from fitting an existing payment workflow, not from collecting another dashboard.
Age is not a barrier here: the app is rated for Everyone. That describes its content suitability, not the financial responsibility required to operate a business account. Anyone using it should still understand the account’s payment conditions, keep access secure, and make sure the person handling transactions is authorized to do so.
My cautious verdict after using it
PayPal Business is a practical mobile companion for small businesses that need to send invoices and monitor PayPal activity without being tied to a desk. I like its clear purpose, free entry point, broad Android compatibility, and usefulness in real situations such as finishing a job and sending the invoice immediately afterward.
Its limitations are just as important. It does not turn a payment account into a complete accounting system, and mobile convenience can encourage rushed decisions if I do not check recipients, amounts, and transaction status carefully. Businesses with complex permissions, large-scale reporting, or specialized invoicing needs should compare it with dedicated tools rather than assuming one app can cover everything.
The best reason to choose PayPal Business is control over routine PayPal tasks from a phone, not the promise of managing every part of a company. I would use it alongside a disciplined bookkeeping process, protect the account as carefully as any other financial service, and review the available account controls before giving anyone else access.
With that realistic expectation, it earns a place on my shortlist for freelancers and small operators who want a straightforward way to handle invoices and payment checks. It is less compelling as the central operating system for a growing business, but for focused, mobile-first PayPal work, PayPal Business remains a useful and sensible option.
Pros
- Manage invoices, payments, and refunds from your phone
- Real-time sales notifications help track incoming transactions
- Supports multiple currencies for international business payments
- Simple tools for sending payment requests to customers
- Transaction history makes bookkeeping and payment tracking easier
Cons
- Business transaction fees can reduce profit margins
- Some features vary by country and account eligibility
- Funds may be temporarily held during security reviews
- Customer support response times can be inconsistent
- Advanced reporting tools are limited compared with full accounting software
FAQs for PayPal Business
What is PayPal Business, and who is it designed for?
PayPal Business is a payment platform for freelancers, online sellers, small companies, and larger merchants who need to accept and manage payments. It can be used to send invoices, receive card or PayPal payments, review transactions, issue refunds, and monitor account activity. The available features may vary depending on your country, business type, verification status, and account settings.
Can I use PayPal Business to accept payments online and in person?
Yes, PayPal Business supports several ways to accept payments, although the exact options depend on your location and eligibility. You may receive payments through PayPal checkout, payment links, invoices, card transactions, or integrations with an online store. Some regions also offer in-person payment tools and card readers. Before downloading, check whether the payment methods you need are supported in your market.
Are there fees for using PayPal Business?
PayPal Business generally does not require a fee simply to download the app or open an account, but transaction, currency-conversion, withdrawal, chargeback, and other service fees may apply. Rates can differ according to the payment type, country, currency, and merchant agreement. It is important to review the official fee schedule before accepting payments, especially if you sell internationally or process frequent refunds.
Is PayPal Business safe for managing company payments?
PayPal Business includes security features such as encrypted transactions, account monitoring, login protection, notifications, and tools for handling disputes or unauthorized activity. You should still protect your account by using a strong, unique password, enabling two-step verification, and checking payment alerts carefully. PayPal may also request identity or business verification, and temporary account limitations can occur when activity requires additional review.
What do I need to create and use a PayPal Business account?
You typically need a valid email address, personal information, business details, and a bank account or eligible card for withdrawals and account verification. Depending on your country and business structure, PayPal may request identification documents, registration information, tax details, or proof of address. Keep your information accurate, because incomplete or inconsistent details can delay verification or restrict certain account functions.

PayPal Business
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via mobile-apps@paypal.com, visit https://www.paypal.com/us/webapps/mpp/business-app, or review their https://www.paypal.com/us/webapps/mpp/ua/legalhub-full.










